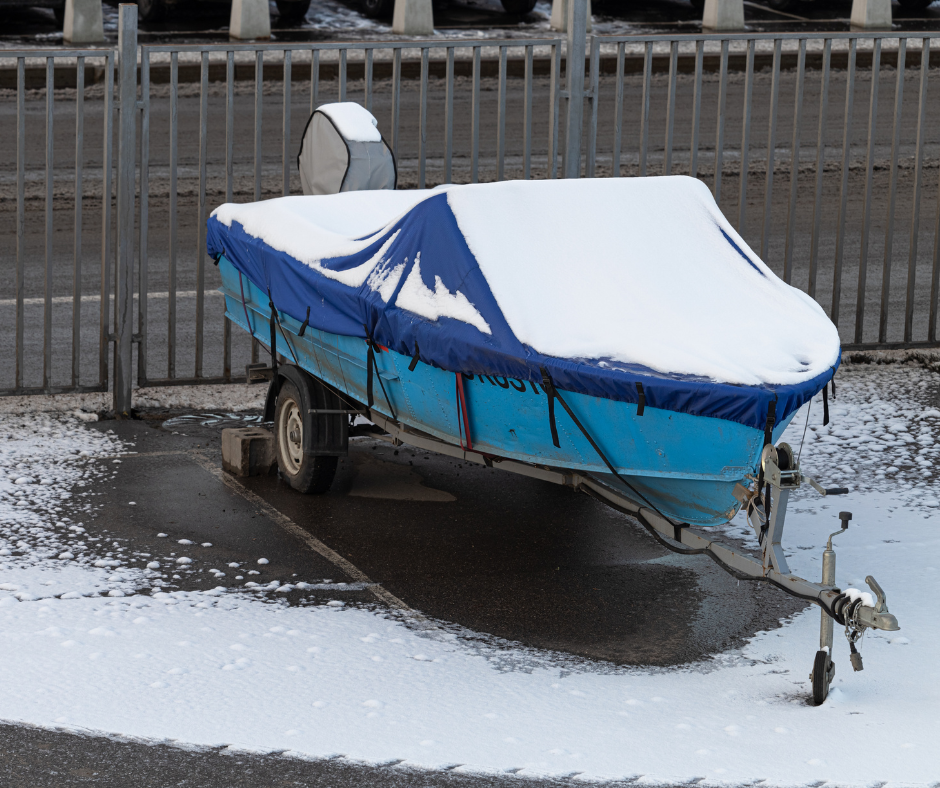
Minnesota winters don’t mess around. Your approach to storing your boat, ATV, or camper trailer shouldn’t, either! Skipping winterization might seem tempting when you’re trying to save a few hours on a busy weekend, but extreme cold, heavy snow, and freeze-thaw cycles can wreak havoc on your recreational equipment if you don’t. Freeze damage could lead to expensive repairs like cracked engine blocks, burst plumbing, and corroded batteries. Those repairs often run into the thousands, and since freeze damage is technically preventable, many insurance policies won’t cover it. The good news, though, is that a few hours of prep work now can save you massive headaches and expensive repairs in the spring. Let’s talk about how to properly winterize your boat, ATV, and RV, plus what to know about storage and insurance along the way. Winterizing Boats for Minnesota Lakes Boats have many moving parts vulnerable to freezing temperatures, so a thorough winterization process matters. You can do this by: Draining all water systems, including the engine, plumbing, and any freshwater tanks Fogging the engine to protect internal components Stabilizing the fuel to prevent it from breaking down over the colder months Removing the battery and storing it somewhere temperature-controlled Cleaning and drying the interior cabin before closing it up If you’re storing your boat outside, don’t forget to invest in a high-quality, properly fitted cover. It’s a small cost compared to the damage that snow, ice, and moisture can cause over a long Minnesota winter. Preparing ATVs, UTVs, and Motorcycles for the Off-Season ATVs, UTVs, and motorcycles need their own round of TLC before you tuck them away for winter. Here’s a quick checklist to get them ready for storage: Change the oil and filter. Add a fuel stabilizer to prevent gas from breaking down and gumming up the carburetor. Either remove the battery or connect it to a tender to keep it charged and healthy. Give everything a thorough cleaning to remove dirt, salt, or grime that can lead to rust. Cover it with a breathable, properly fitted cover. If your vehicle will be sitting for an extended period, you can also put it on a stand or set reminders to periodically roll the tires to prevent flat spots from forming. Getting RVs and Camper Trailers Ready for Winter In Minnesota winters , RVs and camper trailers face many of the same risks as boats. Water left in the system is the number one enemy. Here are some ways to keep them nice and safe so they’re ready for spring: Drain and flush the freshwater tanks, water heater, and plumbing lines. Run RV-specific antifreeze through the system to protect against any remaining water that could freeze and crack pipes or fittings. Disconnect the battery or hook it up to a maintainer. Add fuel stabilizer if your RV has its own engine or generator. Check tire inflation and consider placing them on leveling blocks to avoid flat spots. Thoroughly clean the interior and exterior. Seal up any gaps or vents to keep pests out. A little extra effort now means your RV will be ready to roll the moment warmer weather returns! Storage Location Matters Where you store your recreational winter toys matters just as much as how much you prepare them for the winter months ahead. Indoor storage is always the ideal option. It protects your equipment from the elements and reduces the risk of damage. If indoor storage isn’t available, a high-quality, properly fitted cover can still provide solid protection for boats, ATVs, and RVs sitting outside. No matter where you store your equipment, keep it on level ground and away from potential hazards like falling branches or heavy snow drifts. Also take basic security measures to prevent theft or vandalism. Don’t Forget the Insurance As important as winterizing your vehicles and storing them properly is, don’t forget your insurance policy! Your coverage may look different depending on how and where you store your toys, so it’s always smart to check with your agent before the snow starts falling. If you’ve added a boat, ATV, or camper trailer to your garage this year, make sure your insurance agent knows. Telling them about high-value recreational toys helps ensure you have the right coverage when you need it most. The last thing you want is for something to happen, and then you find out you’re underinsured ! Protect Your Investment This Winter Taking the time to properly winterize and store your boat, ATV, or RV now means you’ll avoid costly repairs (and a lot of frustration!) when the weather finally warms up. Not sure if your current policy covers your recreational toys the way it should? Give our team at Rehm Insurance a call . We’ll review your coverage, make sure your boat, ATV, or RV is properly protected through the winter, and help you head into spring with peace of mind.
Every August, countless Minnesota families send their kids off to college. They have checklists for everything from dorm essentials to school supplies, but one item almost always gets overlooked: renters insurance . If you’re one of those lucky parents gearing up for back-to-college season, let’s talk about what’s actually at risk, when it’s time for your student to get their own policy, and how much you can expect to pay. After this quick review, you’ll be ready for move-in day with one less thing to worry about! What’s Actually at Risk in a Dorm Room or Apartment Most students head off to school with more valuable belongings than their families realize. Add up their laptop, phone, bike, gaming console, mini fridge, textbooks, and a closet full of clothes, and a typical dorm room or first apartment can easily hold $5,000 or more in personal property. If they’re living in a dorm, they’re exposed to some unique risks. Hallway theft happens more often than students expect, especially when doors are propped open or other students are in and out of the rooms. Theft accounts for half of all campus crimes. Bikes, laptops, and cell phones often go missing, as electronics are the most commonly stolen items . Even a burst pipe or accidental fire in a shared building can damage or destroy everything a student owns in minutes. Off-campus apartments carry similar risks, plus a few more. An accidental kitchen fire, faulty door locks, or a break-in while everyone is away at class can all lead to real losses. Most students don’t think about replacement costs until they’re forced to figure out how to afford a new laptop and a new wardrobe at the same time. That’s exactly the gap renters insurance is built to fill. Students: Are You Covered Under Your Parents’ Policy? This is the question we hear most often, and the answer depends on a few key details. Most homeowners policies extend some coverage to a dependent student, but that coverage comes with conditions. Insurance companies typically consider the student’s age, enrollment status, and where they live to determine whether they still qualify as a covered household member. As a general rule of thumb, a full-time student under 24 who lives in a dorm or on-campus housing is usually covered under their parents’ homeowners policy . Coverage typically extends to personal property and liability, though often at a reduced limit than what’s covered at the family home. Off-campus housing changes the picture. Once a student moves into an apartment or house away from campus, many policies no longer automatically extend coverage. Age and enrollment status matter, too. If your student turns 24, drops to part-time enrollment, or graduates, they typically age out of coverage under your policy. These thresholds can also vary by insurance company, so a rule that applied to your kid’s roommate’s policy might not apply to yours. Because these details vary so much between insurance companies, we always recommend calling your independent insurance agent before move-in day rather than assuming you’re all set. Ask specifically what’s covered, what the limits are, and whether the coverage applies to the exact address your student will be living at this year. When Students Need Their Own Renters Policy Not every student fits neatly into the coverage their parents already have. Once a student turns 24, moves off campus, or changes to part-time enrollment, they’ll generally need their own policy. Even students who technically qualify for coverage under their parents’ policy might want their own plan. If your student owns an expensive laptop, camera equipment, or a musical instrument worth more than what the parental policy limit allows, a standalone policy can close that gap. The good news is that none of this needs to be expensive! In many cases, adding renters coverage as an endorsement to an existing family policy costs just a few dollars a month. For students who need a fully separate policy, standalone renters insurance is still one of the most affordable types of coverage available. Either way, the cost is almost always lower than replacing even one stolen laptop out of pocket. What Renters Insurance Actually Covers Renters insurance protects a student’s belongings both on and off campus. If a laptop gets stolen from the library or a bike disappears outside the dorm, coverage applies just as if it happened in the room itself. Liability coverage is just as important. If a friend gets injured in the dorm or apartment, or if your student accidentally damages someone else’s property, this coverage can help cover legal and medical costs. It's a protection most students don’t think about until they need it. Most policies also include additional living expenses. If a fire or burst pipe makes the dorm or apartment temporarily uninhabitable, this helps cover the cost of a hotel or short-term rental while repairs happen. A few common exclusions are worth knowing upfront. Flood damage typically isn’t covered under a standard policy, and neither is normal wear and tear. High-value items like jewelry or musical instruments often need a separate rider for full protection. Action Steps Before Moving to Campus A few simple steps now can prevent a lot of stress and financial loss, later. Here are some things to do before you pack up the van: Call your insurance agent to confirm what’s covered and what isn’t. Take time to understand the deductible and coverage limits for the applicable policy. Create a photo or video inventory of everything heading to school with your student. Walk through the dorm or apartment with a phone camera and narrate what’s there. Consider adding a rider for extra protection, especially if your student has valuable electronic equipment, musical instruments, or jewelry. Sending a student off to college is a big step, and the last thing any family wants is a surprise gap in coverage. If you have questions about your policy or are considering renters insurance, reach out to us ! We can review your current policy, confirm what’s included, and make sure everyone is covered as they should be. It’ll be one less thing to worry about as your student gets comfortable in their new home away from home!
Summer vacation is supposed to be stress-free, but for Minnesota homeowners, the weeks spent away from home introduce a feeling of anxiety they can’t shake. Between unpredictable summer storms, rising humidity, and the increased chance of a break-in, an empty home is more vulnerable than most families realize. A little preparation before you leave can mean the difference between coming home refreshed and coming home to a costly mess. This checklist walks you through everything you need to do before you pack your bags, so you can enjoy every moment of your trip knowing your home is in good hands. Summer-Specific Home Risks Minnesota Homeowners Should Know Most people associate home risks with winter, which is understandable. Frozen pipes, ice dams, and the bitter cold are all real concerns, especially here in Minnesota. But summer brings its own set of challenges that we need to prepare for. Our summers are known for intense thunderstorms that can roll in fast and hit hard. This heavy rainfall can cause basement flooding, particularly in older homes or properties in low-lying areas. Without anyone at home to catch a problem early, a small amount of water in the basement can lead to significant structural damage and mold growth in a matter of days. On top of that, a power outage during a storm can knock out your sump pump just as water is rising in your basement. Heat and humidity pose their own risks, too. If your air conditioning fails while you're away, indoor temperatures and moisture levels can climb quickly. That kind of environment is a breeding ground for mold and can cause damage to wood floors, furniture, or even drywall. Then there’s the security angle. Homes that look visibly unoccupied are a common target for summer break-ins. Overflowing mailboxes, uncut lawns, and houses without lights on are clear signs to burglars that your home is empty. Your Pre-Departure Home Security Checklist Running through a simple checklist before you leave takes less than an hour and can save you from a very unwelcome homecoming. Arrange for someone to pick up your mail and packages. Set timers inside so lights turn on in common areas at night. Make sure every window and door is locked and secured, including side garage doors, basement windows, and sliding glass doors. For longer trips, set up landscaping services so your lawn stays well-kept. Protecting Against Water Damage and Storm Issues Minnesota’s summer storm season brings another very real and serious risk for unattended homes: water damage! Here are some ways that you can protect your home from costly water damage: Clear out gutters and downspouts Check that your sump pump is working properly Consider turning off your home’s main water supply to eliminate the risk of a burst pipe or slow leak causing issues Unplug non-essential appliances and electronics to prevent a power surge during a summer storm A few minutes of preparation before you leave can protect both your belongings and your home – and your peace of mind! What Your Homeowners Insurance Covers (and Doesn't) Even when you've done everything right, sometimes things still go wrong. That's exactly what homeowners insurance is there for! Going over your policy before you leave will help you feel more comfortable staying away for longer periods. Most standard homeowners policies cover sudden, unexpected events like storm damage, fire, theft, and certain types of water damage. For example, if a tree falls on your roof during a storm or someone breaks in while you're away, it will typically be covered. What generally isn’t covered is damage that results from negligence. If the problem was foreseeable and preventable but ignored, that could cause issues in your claim. For example, if your sump pump has been failing for months and you didn't address it before leaving, a resulting flood may not be fully covered. Insurance companies often look at whether the homeowner exercised "reasonable care" in maintaining and protecting their property. As you go through your prevention checklist, document exactly what you did. Take photos of your home's condition before your trip, keep receipts for any maintenance work you have done, and hold on to any records of sump pump inspections or appliance servicing. That documentation can come in handy if your claim is disputed. Smart Technology and a Communication Plan Take your preparation to the next level by pairing it with a few smart home tools for an added layer of protection. Tools like water leak sensors placed near appliances, water heaters, and sump pumps, a smart thermostat, or security cameras can help keep your home safe and sound while you’re enjoying your time away. In addition to these smart tools, always ask a trusted neighbor, friend, or family member to keep an eye on your home while you’re gone. Make sure your emergency contact has everything they need to act quickly if something comes up: a spare key, your alarm code, your insurance agent's number, and a way to reach you while you're traveling. Before You Go: Key Takeaways A summer vacation should leave you feeling refreshed, not anxious about what might be happening back home. The steps covered in this guide are smart habits that every Minnesota homeowner should build into their pre-trip routine. Here's a quick recap of the most important things to do before you leave: Make your home look lived in with light timers, collected mail, and maintained landscaping Lock all doors and windows Clear gutters, test your sump pump, and consider shutting off the main water supply Unplug non-essential electronics and appliances to guard against power surges Set up smart home sensors and give a trusted contact everything they need to act in an emergency Document your pre-departure steps in case you ever need to support an insurance claim One more thing that belongs at the top of every pre-vacation checklist: making sure your homeowners insurance coverage is actually up to the job. Policy details matter, and gaps in coverage have a way of showing up at the worst possible time. Before you head out this summer, take a few minutes to review your homeowners policy with the team at Rehm Insurance. As Mankato's locally owned, independent agency, we know Minnesota homes and the risks they bring. We'll make sure your coverage is solid so you can enjoy every day of your trip with total peace of mind. Give us a call at (507) 345-3366 or request a free quote online today.